Category
Business
Finance and tax essentials for Moroccan businesses and auto-entrepreneurs - from invoicing and VAT obligations to the unified professional contribution (CPU) and corporate tax.
5 articles about Business
Business
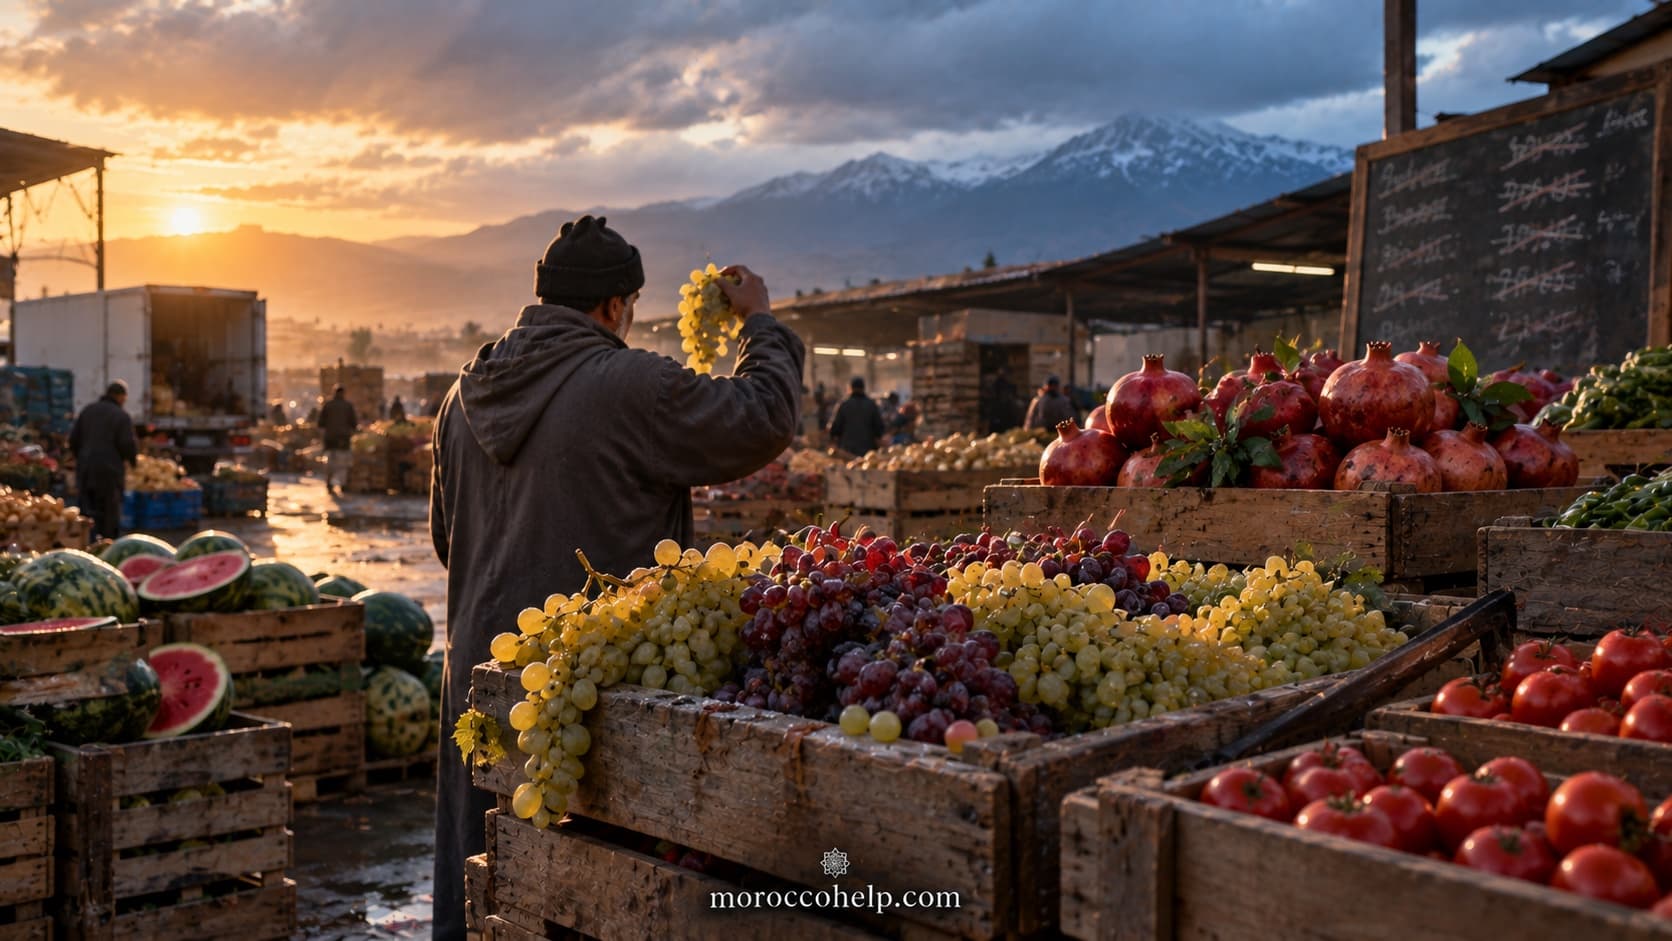
Fresh Produce Risk Brief: Week of September 14, 2026, Falling Prices, Fragile Goods, and Where to Put Your Cash
A finance-first read of Morocco's wholesale fruit and vegetable market for the week of September 14, 2026. Grapes down from 11 to 7 DH/kg (-36% mark-to-market in one week), watermelon in distress at 0.50 DH/kg, tomatoes cheap today but set to rise after the Souss-Massa storm damage. Price charts, a risk matrix, the onion export policy file, position sizing and the spoilage math every grossiste should run before buying.
Marouan Tazi·10 min read
Read article
Business
Bookkeeping in Morocco (2026): Law 9-88 Rules, E-Invoicing, Deadlines, Penalties & Costs
Bookkeeping in Morocco explained for 2026: Law 9-88 and CGNC requirements, the mandatory books, the new electronic accounting and e-invoicing rules (Article 145-IX), VAT and tax deadlines via SIMPL, penalties, retention periods, and what an expert-comptable costs.
Salah-eddine Bennani·11 min read
Read article
Business
RAS on Services 2026: The Turnover Threshold Expanding Withholding for Companies
From 1 July 2026, Morocco extends withholding tax on service fees to companies above a progressive turnover threshold (≥ 500 MDH, then 350/200), plus a 5% RAS IS and the RAS TVA (75% / 100%). Practical guide for B2B invoicing, cash flow, and the attestation de régularité fiscale.
Marouan Tazi·5 min read
Read article
Business
Morocco Corporate Income Tax 2026: Two-Rate Scale and Reform Complete
Morocco's corporate income tax (IS) reform is finished in 2026: two-rate scale of 20% and 35% based on a MAD 100 million threshold. Rates, minimum contribution, exemptions and Finance Law 2026 changes explained.
Marouan Tazi·3 min read
Read article
Business
Auto-Entrepreneur in Morocco 2026: How the CPU Tax Works
Morocco has over 250,000 active auto-entrepreneurs paying the CPU (Contribution Professionnelle Unique) instead of separate IR, professional tax and CSS. Rates, ceilings, eligibility and obligations for 2026.
Marouan Tazi·3 min read
Read article