It is one of the quiet shifts of this autumn's economic news. Except that it is no longer so quiet on OCP's books: China, the world's largest phosphate producer, is sharply cutting its fertilizer exports to prioritise its domestic market, while the Middle East crisis has tripled the price of sulfur, the number-one input of phosphate fertilizers. The result of an exceptionally brutal first half of 2026: OCP posted a net loss of MAD 2.84 billion (against a MAD 8.25 billion profit a year earlier), yet held its EBITDA margin at 28% (where Mosaic fell to 9% and Nutrien to 8%) and gained world market share, up from 28% to 30%. A data-driven deep dive into the two-way traffic between Asian markets, Gulf geopolitics and the Moroccan economy, in a global context we were already tracking in our late-September international markets brief.
What is happening in China (and Asia)
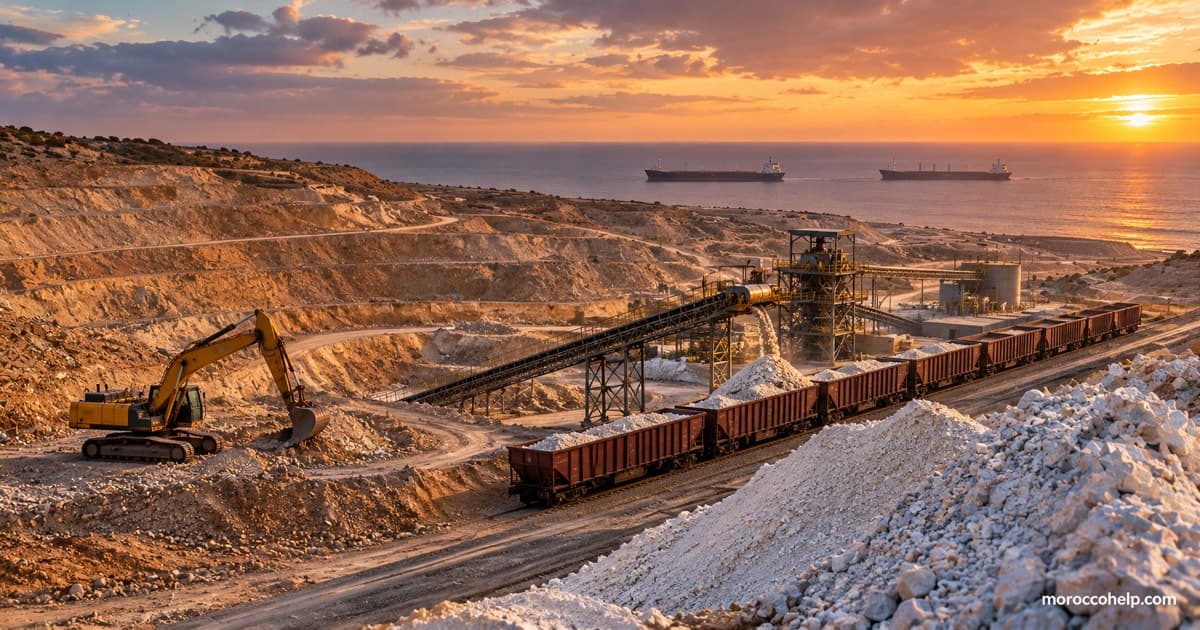
As the top producer, China has dried up a large share of its phosphate fertilizer exports: Beijing now prioritises its domestic market, to the point that analysts speak of a "collapse" of Chinese export flows. OCP confirms it in its half-year report: global supply remains constrained by "the continued absence of Chinese phosphate exports", compounded by reduced Russian volumes into Europe and lower Saudi exports.
The direct consequence: global nutrient supply tightens. A fertilizer buyer who used to source cheaply from China must now turn to the other major suppliers, and bid more aggressively for available volumes. That is precisely the void in which Moroccan phosphate becomes strategic.
Add a lesser-known but spectacular trade link: in May 2026 Morocco became the top destination of China's ammonia exports, absorbing more than a quarter of Chinese shipments during a record month, feeding OCP's fertilizer plants with a key nitrogen input whose price exploded elsewhere.
The shock from the Strait of Hormuz
While China closes the fertilizer taps, another strait hit the sulfur one. The war in Iran and disruptions in the Strait of Hormuz, the transit route of roughly 45% of the world's seaborne sulfur exports (more than 35% of urea, 25% of ammonia and 20% of phosphate), sent prices into the stratosphere:
- Average Moroccan sulfur import price: MAD 5,490 per ton from January to July, up 182% year on year, according to a September report from the Ministry of Economy and Finance.
- Total bill: MAD 27.2 billion ($2.8bn) of sulfur imported from January through August, up almost 190% year on year, per Exchange Office data. August alone added about MAD 7 billion (+35% versus July).
- The scissors: over the first half, sulfur prices tripled while fertilizer prices rose only about 20%: impossible to pass such a shock on to farmers already squeezed on affordability.
Morocco sources its sulfur from Kazakhstan, Saudi Arabia and the UAE, and has opened talks with Iraq to secure additional volumes.
The Moroccan numbers: the half-year in tables
| Indicator | Figure | Detail |
|---|---|---|
| Phosphate & derivatives exports (Jan-Aug) | MAD 61bn, -6% | Exchange Office data |
| Sulfur imports (Jan-Aug) | MAD 27.2bn, +190% | Avg price MAD 5,490/t (+182%) Jan-Jul |
| OCP revenue (H1 2026) | MAD 48.37bn, -7.3% | Versus MAD 52.17bn in H1 2025 |
| OCP EBITDA (H1) | MAD 13.31bn, -28% | Margin 28% (36% a year earlier), 27% in Q2 |
| Net result, group share (H1) | -MAD 2.84bn | Versus +MAD 8.25bn in H1 2025 |
| Global phosphate fertilizer trade (H1) | -22% | Indian, European and African demand down |
| Moroccan fertilizer exports (H1) | -16% | Better than the market → world share 28% → 30% |
| Bank Al-Maghrib forecast (2026) | +9.7% phosphate exports | A bet on a year-end acceleration |
The net loss is mechanical: the rise in the sulfur bill alone exceeds the decline in EBITDA, and the financial charges of a large debt complete the reversal. But the operating read remains solid, the very paradox of this half-year.
OCP ahead of its rivals: the comparison that says it all
OCP's half-year report includes an international comparison worth a look. EBITDA margins of phosphate activities in H1 2026:
| Group | H1 2026 EBITDA margin | Phosphate EBITDA change |
|---|---|---|
| Ma'aden (Saudi Arabia) | 33% | -34% to -51% (sector range) |
| OCP (Morocco) | 28% | -26% (in dollars, comparable basis) |
| PhosAgro (Russia) | 22% | n.d. |
| ICL (Israel) | 19% | n.d. |
| Mosaic (United States) | 9% | n.d. |
| Nutrien (Canada) | 8% | n.d. |
Ma'aden's edge comes from its domestic access to sulfur and ammonia; the others pay full price. Symbol of the shock: at Mosaic in Brazil, phosphate capacity utilisation fell from 84% to 47% between Q2 2025 and Q2 2026, the Patrocínio mine was placed on care and maintenance, and Brazilian rock production dropped from 1 million to 0.7 million tons. Meanwhile OCP kept supplying customers, and Brazil, the most resilient market, saw Moroccan sales grow.
OCP's response: TSP, Chinese ammonia and a US return
Facing the input shock, the group did not sit still:
- The TSP pivot. Triple superphosphate requires far less sulfur and no ammonia. It rose from 26% to 35% of OCP's exported fertilizer volumes in the first half, and a third TSP line with a 1-million-ton capacity started up at Jorf Lasfar in July.
- Stocks secured ahead of time. OCP had bought its sulfur before the surge, back in late 2025, and diversified its sources, including Chinese ammonia (Morocco, top destination in May).
- Anticipated maintenance. Supply disruptions forced works touching about 30% of production capacity; part of the programme was moved forward to Q2 to preserve second-half flexibility.
- The US market return. Washington suspended countervailing duties on Moroccan phosphates on June 29 (for up to 8 months), citing a fertilizer shortage; OCP resumed US exports in July and August.
- Specialty products on the rise: the Specialty Products & Solutions division grew 26% to MAD 4.76 billion.
On the balance sheet: MAD 16.07 billion invested in H1 (up year on year), MAD 32.69 billion of cash, net financial debt at MAD 115.47 billion (3.05× EBITDA versus 2.76× at end-2025), and market access confirmed by a $1.5bn international hybrid issuance oversubscribed more than four times.
Good news or bad news? Both at once.
Tailwinds: prices supported by China's retreat, world market share up (28% → 30%), ~70% of world phosphate reserves, and freshly expanded capacity to absorb Asia's orphan demand.
Headwinds: a sulfur bill up 190%, a MAD 2.84 billion net loss, a strong dollar making every imported input pricier (see our dirham vs euro and dollar analysis) and the risk of a brutal reversal if China reopens its exports.
Why it matters for the Moroccan economy
Phosphates are the kingdom's third-largest export sector, behind automotive and agri-food industries. Three transmission channels:
- FX revenues: MAD 61 billion over 8 months, a flow that supports foreign reserves and, incidentally, the dirham.
- Local jobs and investment: the Khouribga, Jorf Lasfar and Benguerir sites carry entire regions.
- Equities and confidence: OCP's results weigh on how the Casablanca Stock Exchange prices the commodity cycle, after a September already hard on the MASI (see our September 28 close brief).
FAQ
Why are Chinese phosphate exports so important?
China is the world's largest producer. When it withdraws from the export market, millions of tons of fertilizer vanish from global supply, and buyers fall back on other suppliers, Morocco first among them, pushing prices up.
Why did sulfur prices rise so much?
The war in Iran and disruptions in the Strait of Hormuz, through which roughly 45% of the world's seaborne sulfur exports transit, abruptly tightened supply. Morocco's average import price rose 182% year on year (MAD 5,490 per ton, January to July).
Is OCP in trouble?
OCP posted a MAD 2.84 billion net loss in the first half, but its EBITDA margin (28%) beats almost every competitor, its cash position remains solid (MAD 32.7 billion), investment is rising and it is gaining world market share. It is an absorbed cost shock, not a structural failure.
How does OCP reduce its sulfur dependence?
By accelerating TSP (a fertilizer needing little sulfur and no ammonia, now 35% of exported volumes), by securing stocks and sources ahead (including Chinese ammonia), and by bringing maintenance forward.
What is the impact on Moroccan farmers?
A tight global market supports fertilizer prices. Locally, the national fertilizer subsidy programme absorbs part of the shock, but the overall bill remains on an upward trend.
What does Bank Al-Maghrib expect?
The central bank expects phosphate exports to rise 9.7% over 2026, a bet on accelerating volumes, and on Asian tailwinds holding.
Read more
- International markets brief, 29 September 2026
- Dirham vs euro and dollar, 5 October 2026
- Casablanca Stock Exchange: 28 September 2026 close
Yassine follows the Casablanca Stock Exchange, Bank Al-Maghrib decisions and Morocco's macroeconomic indicators. He translates market moves into clear, practical takeaways for Moroccan investors and savers.